What is the baseline market overview of the Mobile Pharmacy Vehicle Market?
The Mobile Pharmacy Vehicle Market represents a vital convergence of automotive engineering and healthcare delivery, valued at 1.71 Billion in 2026. This sector encompasses specialized rolling stock—including Heavy-Duty Pharmacy Trucks and Refrigerated Pharmacy Vans—designed to bridge the last-mile healthcare gap in remote and underserved geographies.
Structural Growth Drivers and Market Restraints
Our analysis indicates that rising demand for decentralized healthcare and government health-outreach initiatives act as primary structural drivers. Conversely, stringent compliance mandates from regulatory bodies like the FDA regarding cold-chain storage and high chassis customization costs serve as notable operational restraints.
Emerging Trends in the Mobile Pharmacy Vehicle Industry
The industry trends show a definitive shift toward sustainable propulsion, with Electric Healthcare Vehicles and Solar-Powered Healthcare Vehicles gaining rapid traction. Fleet operators are prioritizing zero-emission platforms to meet urban environmental mandates while powering onboard refrigeration systems.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic exposed vulnerabilities in static supply chains, catapulting the Mobile Pharmacy Vehicle industry into the spotlight for emergency vaccine distribution. Post-COVID recovery trajectories reflect sustained government funding for Disaster Relief Trucks and Emergency Pharmacy Vans to fortify pandemic-preparedness infrastructure.
Competitive Landscape and Market Concentration
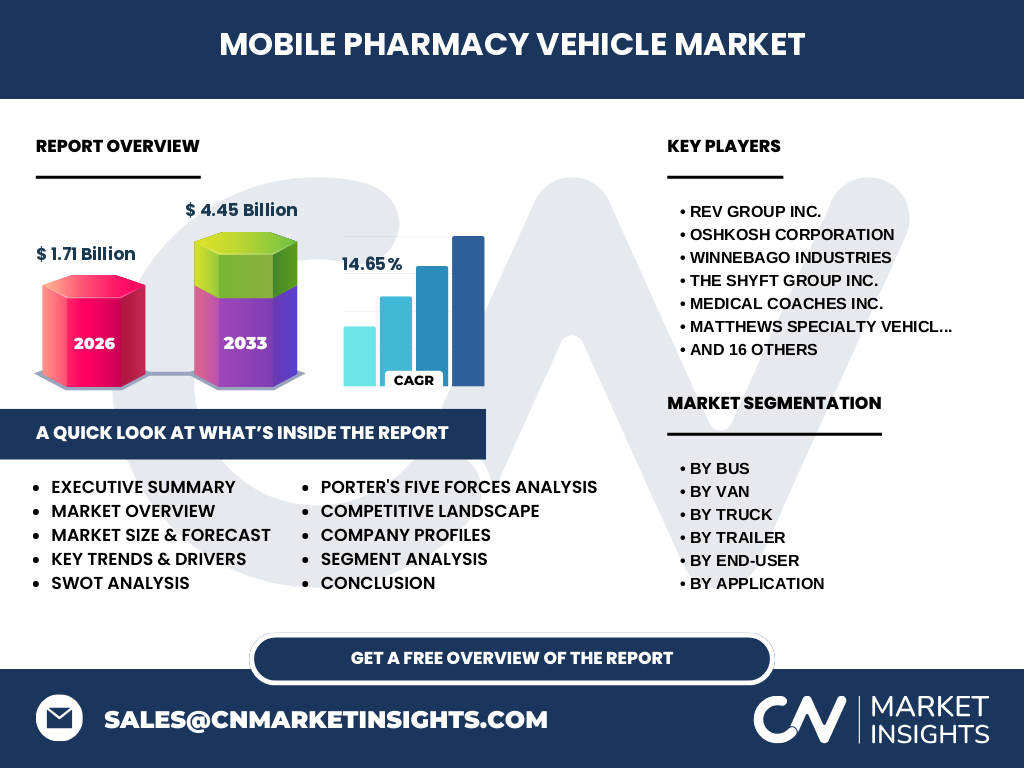
The competitive landscape is moderately consolidated, featuring established heavyweights such as REV Group Inc., Oshkosh Corporation, and Winnebago Industries. These industry leaders leverage advanced manufacturing capabilities to supply customized Multi-Specialty Medical Buses to federal and private healthcare networks.
Executive Summary of the Mobile Pharmacy Vehicle Market
This comprehensive research report highlights a robust market expansion driven by technological integration and rural outreach imperatives. The Mobile Pharmacy Vehicle market size is poised for exponential adoption through the next decade.
Market Forecast and Long-Term Projections
Our research forecasts the market to expand from 1.71 Billion in 2026 to reach 4.45 Billion by 2033, expanding at a remarkable CAGR of 14.65%. This aggressive growth trajectory underscores the permanent transition toward ambulatory medical infrastructure.
Segmentation Analysis Across Vehicle Types and End-Users
The market segments by bus, van, truck, and trailer configurations, catering to diverse operational needs. End-users span hospitals, government agencies, and non-governmental organizations deploying Mobile Healthcare Buses and Expandable Medical Trailers for targeted community interventions.
Regional Market Analysis and Geographic Performance
Geographic performance varies significantly, with North America leading adoption due to well-established emergency response frameworks. Meanwhile, Asia-Pacific represents a high-growth frontier driven by expanding rural healthcare access and targeted government welfare transport programs.
In-Depth Regional Review
Regional reviews indicate that North American demand is anchored by federal disaster relief procurement, whereas European markets prioritize eco-friendly, low-emission compact medical vans for urban outreach. Emerging economies focus heavily on cost-effective community outreach buses.
Company Profiles and Strategic Positioning
Key industry participants like The Shyft Group Inc., Medical Coaches Inc., and Matthews Specialty Vehicles Inc. differentiate themselves through proprietary chassis engineering and modular interior fit-outs tailored for pharmaceutical dispensing compliance.
Porter's Five Forces Analysis
Porter's framework reveals moderate-to-high supplier power due to specialized chassis requirements, coupled with intense competitive rivalry among custom vehicle builders. Buyer power remains tempered by strict medical certification requirements that necessitate specialized manufacturing expertise.
SWOT Analysis of the Industry
Key strengths include high vehicle customization and mobility; weaknesses involve high initial capital expenditure. Opportunities lie in electrification and rural expansion, while threats include chassis supply chain bottlenecks and rising raw material costs.
Value Chain Analysis
The value chain flows from raw steel and aluminum procurement through specialized chassis manufacturing, medical equipment integration, and final deployment by hospitals and NGOs. Maintaining strict cold-chain integrity remains the critical link throughout distribution.
Investment Insights and High-Potential Areas
Strategic recommendations highlight Electric and Hybrid Medical Service Vehicles as prime investment targets. Investors should focus on manufacturers incorporating solar-assisted power to reduce operational downtime in off-grid deployments.
Conclusion and Key Takeaways
The Mobile Pharmacy Vehicle Market offers compelling growth backed by a 14.65% CAGR. Stakeholders must embrace modular, eco-friendly designs to capture high-margin opportunities in both urban outreach and disaster relief verticals.
Research Methodology
Baseline estimates are meticulously triangulated by combining trade registry data, primary executive interviews with key players like Odulair LLC and LDV Specialty Vehicles Inc., and secondary macroeconomic health-expenditure indicators.
Scope of the Report
This report covers global deployment trends across van, truck, bus, and trailer configurations from 2027 to 2033. Analysis focuses on commercial, governmental, and non-profit mobile pharmacy applications while excluding static retail pharmacy infrastructure.
Recent Developments in the Sector
Recent strategic moves feature major announcements regarding electric vehicle chassis partnerships and expanded production lines by firms like Craftsmen Industries Inc. and Farber Specialty Vehicles LLC, aimed at meeting surging demand for advanced telehealth units.